Drowning in EMIs? Loan Consolidation Could Turn 5 Loans Into 1
Juggling multiple EMIs? Here's how loan consolidation works in India, what it costs, and when it's actually worth doing...
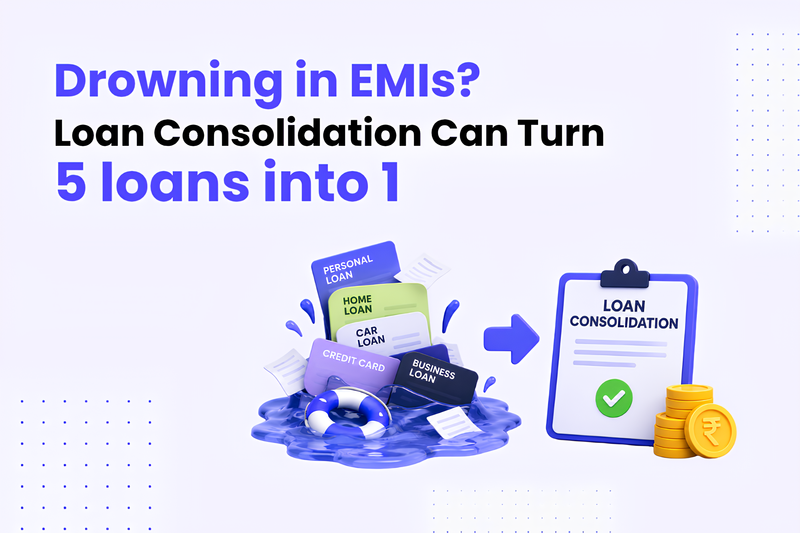
If your phone buzzes with five different EMI reminders on five different dates, you're not managing loans anymore, you're that one relative running between five tables at a wedding, refilling everyone's plate the moment they wave at you, except these guests charge you interest for making them wait. Loan consolidation is how you stop running between tables altogether: you take out one new loan, use it to pay off everything else, and walk away with a single EMI, a single due date, and (usually) a lower total outgo.
Already juggling too many EMIs to keep straight?
The Rubber Band Test
Here's a quick way to know if you're a consolidation candidate: imagine your salary is a rubber band. Every EMI stretches it a little. One or two loans, the band stretches and snaps back fine every month. But add a third, fourth, fifth EMI, credit card minimum due, a BNPL installment, and the band doesn't snap back anymore. It just stays stretched. That's the sound of your finances losing their elasticity.
You're a strong candidate for consolidation if:
You're juggling three or more EMIs and the due dates live in your head like exam dates you're dreading
Your total EMI outgo has crossed roughly 40 to 50% of your take-home pay
You've got expensive credit card debt sitting next to cheaper personal loan debt, quietly dragging your average interest rate up
You're still paying on time, just barely
That last point matters more than people think.
Why "Just Combine Them" Isn't the Whole Story
Picture two friends, Aditi and Rohan, both carrying roughly Rs 6 lakh in combined debt across a personal loan and two credit cards.
Aditi consolidates the smart way: she lists every debt, checks what EMI her salary can actually absorb, compares three lenders, and picks a loan that closes all three accounts and drops her blended interest rate from around 28% (credit card heavy) to 14%. Her EMI drops from Rs 34,000 to Rs 21,000.
Rohan consolidates in a hurry: he takes the first offer his bank pushes on him, doesn't check the processing fee, and ends up with a longer tenure that technically lowers his EMI but adds nearly Rs 90,000 in extra interest over the life of the loan.
Same starting debt. Same word, "consolidation." Two very different outcomes. The difference wasn't whether they consolidated, it was whether they did the homework first.
What to Have Ready Before You Even Apply
Think of this like packing for a trek. Show up without the right gear and the mountain doesn't care how motivated you are.
A full debt map. Every loan, every card, with outstanding balance, interest rate, and remaining tenure, in one sheet. Not in your head, not "roughly."
Proof of income. Last 3 to 6 months of salary slips or bank statements, ready to go.
A fresh credit report. Not the one you checked eight months ago when things looked different.
A number. Work out the maximum EMI your budget can actually absorb before you start comparing offers. Otherwise you'll anchor to whatever the lender offers instead of what you can afford.
The Actual Process, Step by Step
Map the damage. List every debt with balance, rate, and tenure. This is your before-picture.
Run the eligibility math. Lenders typically want your total EMIs, including the new one, to stay under a set share of your income (often 40 to 50%, though this varies).
Shop the route. Bank, NBFC, or a platform that matches you to a lender, more on this below.
Apply with everything in hand. Income proof, existing loan details, the works. This is where having your debt map ready saves you weeks.
Let the new loan do the paying. Once disbursed, the funds go toward closing your old accounts, not into your pocket first.
Get proof, not promises. A closure letter or NOC for every old account. Verbal confirmation from a call center doesn't count.
Check your credit report a few weeks later. Confirm the old accounts show as closed, not just "settled" or still open.
Budget four to six weeks from application to your old accounts actually showing closed. Anyone promising same-day full consolidation is usually selling you something else.
Bank vs NBFC vs a Matched Platform
The honest way to think about this: it's not really bank vs NBFC vs platform, it's "how much of this legwork do you want to do yourself." Nobody's route is wrong, it's a trade of your time for someone else's comparison shopping.
The Landmine Nobody Warns You About
Don't close your old accounts yourself the moment you get approved. Wait until the new loan has actually disbursed and paid them off, and you have closure confirmation in writing. Closing too early, or even just stopping payments while you "wait for the process," can leave a gap that shows up as a missed payment on your report, which defeats the entire purpose of consolidating in the first place.
Also get the total cost of the new loan in writing, not just the monthly EMI. A lower EMI stretched over a longer tenure can quietly cost you more overall. The EMI is the monthly headline, the total cost is the real story.
If You've Already Fallen Behind, This Isn't Your First Move
Consolidation assumes you're still current, or close to it. If you're already getting recovery calls, have missed a couple of payments, or a lender has started sending notices, taking on a brand new loan usually isn't the fix, lenders are unlikely to approve fresh credit for someone already behind, and stacking new debt on top of trouble tends to make things worse, not better.
That's a different conversation: negotiating what you already owe down to something manageable, understanding your rights around recovery calls, and getting the harassment (if any) to stop through the right channels rather than taking on more borrowing. If that's closer to where you are, that's worth reading up on separately rather than trying to consolidate your way out of it.
Quick Checklist Before You Apply
Full list of debts with balance and rate
Income proof in hand
Fresh credit report pulled
Maximum affordable EMI worked out
Route chosen: bank, NBFC, or matched platform
If every box is ticked, you're actually ready. If two or three aren't, you're still in the planning phase, and that's fine, rushing this step is exactly how people end up like Rohan.
Not sure consolidation is the right move for you?
Credfix
When debt feels overwhelming, we help you understand what comes next. Get practical guidance on missed EMIs, recovery calls, legal notices, settlement options, and your rights - explained simply, so you can make informed decisions.
Visit SiteEvery loan has a way out. Find yours.
Know your options. Take control.